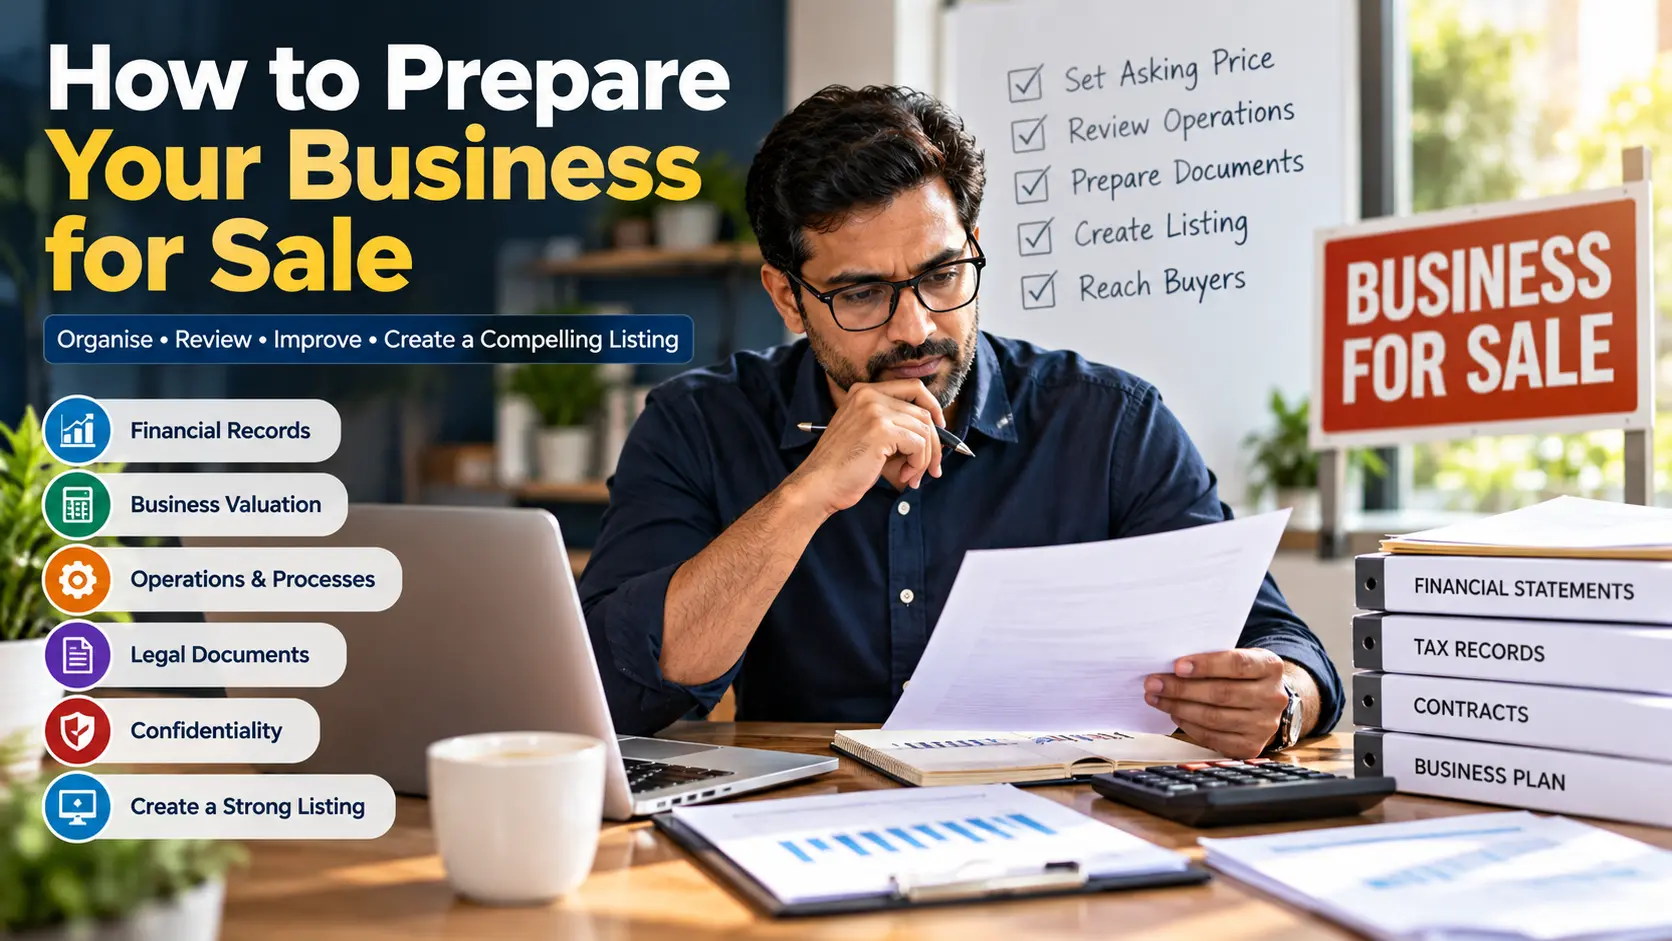
Selling a business involves more than finding a buyer. Before advertising your business, it is important to organise your financial records, understand its value, review daily operations, and prepare accurate information for potential buyers.
A well-prepared business listing can help buyers understand what you are offering and decide whether they want to make an enquiry. Preparation also helps you respond more confidently when buyers ask questions about revenue, expenses, customers, employees, and future opportunities.
Affiliate disclosure: This article contains an affiliate link. If you purchase through the link, we may earn a commission at no additional cost to you. Our guidance is intended to help business owners make informed decisions.
1. Understand Why You Want to Sell
Start by identifying your reasons for selling. Your motivation can influence your timeline, asking price, and preferred type of buyer.
Common reasons include:
- Retirement or a change in personal circumstances
- Starting another business or pursuing a new opportunity
- Relocating to another city or country
- Reducing personal involvement in day-to-day operations
- Realising the value built up in the business
- Selling because of changing market conditions
Decide whether you want a quick exit or have time to wait for a suitable offer. Also consider whether you are willing to remain involved during a transition period.
Having clear objectives makes it easier to evaluate offers beyond the headline price.
2. Organise Your Financial Records
Financial information is one of the first areas serious buyers may want to examine. Incomplete or inconsistent records can create uncertainty and delay negotiations.
Prepare the following documents where applicable:
- Profit and loss statements for recent financial years
- Balance sheets and cash flow statements
- Tax returns and relevant tax filings
- Bank statements and accounting records
- Details of outstanding loans and liabilities
- Accounts receivable and accounts payable
- Inventory records and asset lists
- Revenue breakdowns by product, service, or customer segment
Use accurate figures and ensure that your records are consistent. If personal expenses are included in business accounts, discuss with your accountant how these should be presented appropriately.
Do not exaggerate profits or present forecasts as guaranteed results. Buyers need a realistic picture of the business.
3. Review Your Business Valuation
Before setting an asking price, develop a realistic understanding of what your business may be worth.
Valuation can depend on several factors:
- Historical revenue and profitability
- Cash flow and recurring income
- Business assets and liabilities
- Customer retention and concentration
- Industry conditions and market demand
- Growth opportunities
- Dependence on the owner
- Comparable businesses and recent transactions, where reliable data is available
Different businesses require different valuation methods. Some may be assessed using earnings multiples, while others may depend more heavily on assets, cash flow, or strategic value to a buyer.
Avoid choosing a price based only on the amount you invested or the price you hope to receive.
Consider consulting a qualified accountant, business valuer, or transaction adviser. A professional valuation may help you justify your asking price and prepare for negotiations.
4. Make Daily Operations Easier to Understand
A business that depends entirely on its owner may appear more difficult to acquire than one with documented processes and clear responsibilities.
Review how the business operates when you are not personally handling every task.
Consider preparing:
- Standard operating procedures
- Employee roles and reporting structures
- Supplier and service-provider information
- Customer enquiry and sales processes
- Inventory and quality-control procedures
- Software subscriptions and essential systems
- Regular reporting and performance measures
Documenting these processes can help a potential buyer understand how the business runs and what would be required to take over.
Where possible, reduce unnecessary dependence on a single employee, supplier, or customer. Do not make major operational changes solely for a sale without considering their cost and likely benefit.
5. Review Legal Documents and Business Agreements
Buyers may want to confirm that the business has the necessary rights, registrations, and agreements to operate.
Depending on your business and location, review:
- Business registration documents
- Licences and permits
- Lease or property agreements
- Customer and supplier contracts
- Employment agreements
- Intellectual property registrations
- Insurance policies
- Loan agreements and security interests
- Pending disputes or regulatory matters
Check whether important contracts contain restrictions on transferring ownership or require consent from another party.
Resolve outstanding issues where practical and disclose material matters appropriately. Consult a qualified legal professional for advice about the sale process and any required transfer approvals.
6. Reduce Unnecessary Dependence on the Owner
Ask yourself an important question: could the business continue operating if you were unavailable for several weeks?
If the answer is no, identify the tasks that depend most heavily on you.
You may be able to improve transferability by training staff, documenting customer relationships, delegating routine decisions, and establishing repeatable sales and service processes.
This does not mean removing the owner's expertise from the business. It means helping a prospective buyer understand how that expertise can be transferred or replaced after the sale.
7. Prepare a Clear Business Overview
Before advertising your business, create a concise summary that explains what you are selling.
Your overview might include:
- Business type and industry
- Location and service area
- Years in operation
- Main products or services
- Target customers
- Revenue and profitability information, where appropriate
- Employees and operating model
- Assets included in the sale
- Growth opportunities
- Reason for sale, if you are comfortable disclosing it
Be specific about what is included and excluded. For example, clarify whether the sale includes inventory, equipment, intellectual property, a website, or other assets.
Use evidence to support important claims. Avoid vague statements such as “guaranteed growth” or “unlimited profit potential.”
8. Protect Confidential Business Information
Confidentiality matters, particularly when employees, customers, suppliers, or competitors are unaware of a planned sale.
Consider how much information should appear in your public listing. You may be able to describe the industry, general location, operating history, and business model without immediately disclosing the business name or sensitive financial details.
Before sharing detailed financial records, customer information, or proprietary documents, consider using a confidentiality agreement and a controlled document-sharing process.
Verify a prospective buyer's identity and suitability before providing sensitive information. Follow applicable privacy and data-protection requirements.
9. Create an Effective Business-for-Sale Listing
Once your preparation is complete, turn the information into a listing that helps suitable buyers assess the opportunity.
A strong listing should contain:
A clear headline: Explain the type of business and its main appeal without making unsupported claims.
A useful description: Cover the business model, products or services, target market, and operating structure.
Relevant financial information: Present accurate figures and explain the period they cover. Disclose sensitive details only through an appropriate process.
Included assets: Clarify which equipment, inventory, contracts, or other assets are part of the proposed sale.
Growth opportunities: Identify realistic ways a new owner might develop the business, without guaranteeing future performance.
A clear next step: Tell interested buyers how they can request further information or submit an enquiry.
Proofread the listing before publication. Incorrect figures, unclear terms, and exaggerated claims can undermine buyer confidence.
10. Choose Where to Advertise Your Business
The right advertising channel depends on your business type, location, asking price, and target buyer.
Potential channels include:
- Business-for-sale marketplaces
- Industry-specific business networks
- Professional advisers and business brokers
- Relevant trade associations
- Existing business contacts, where appropriate
- Your own website or professional network
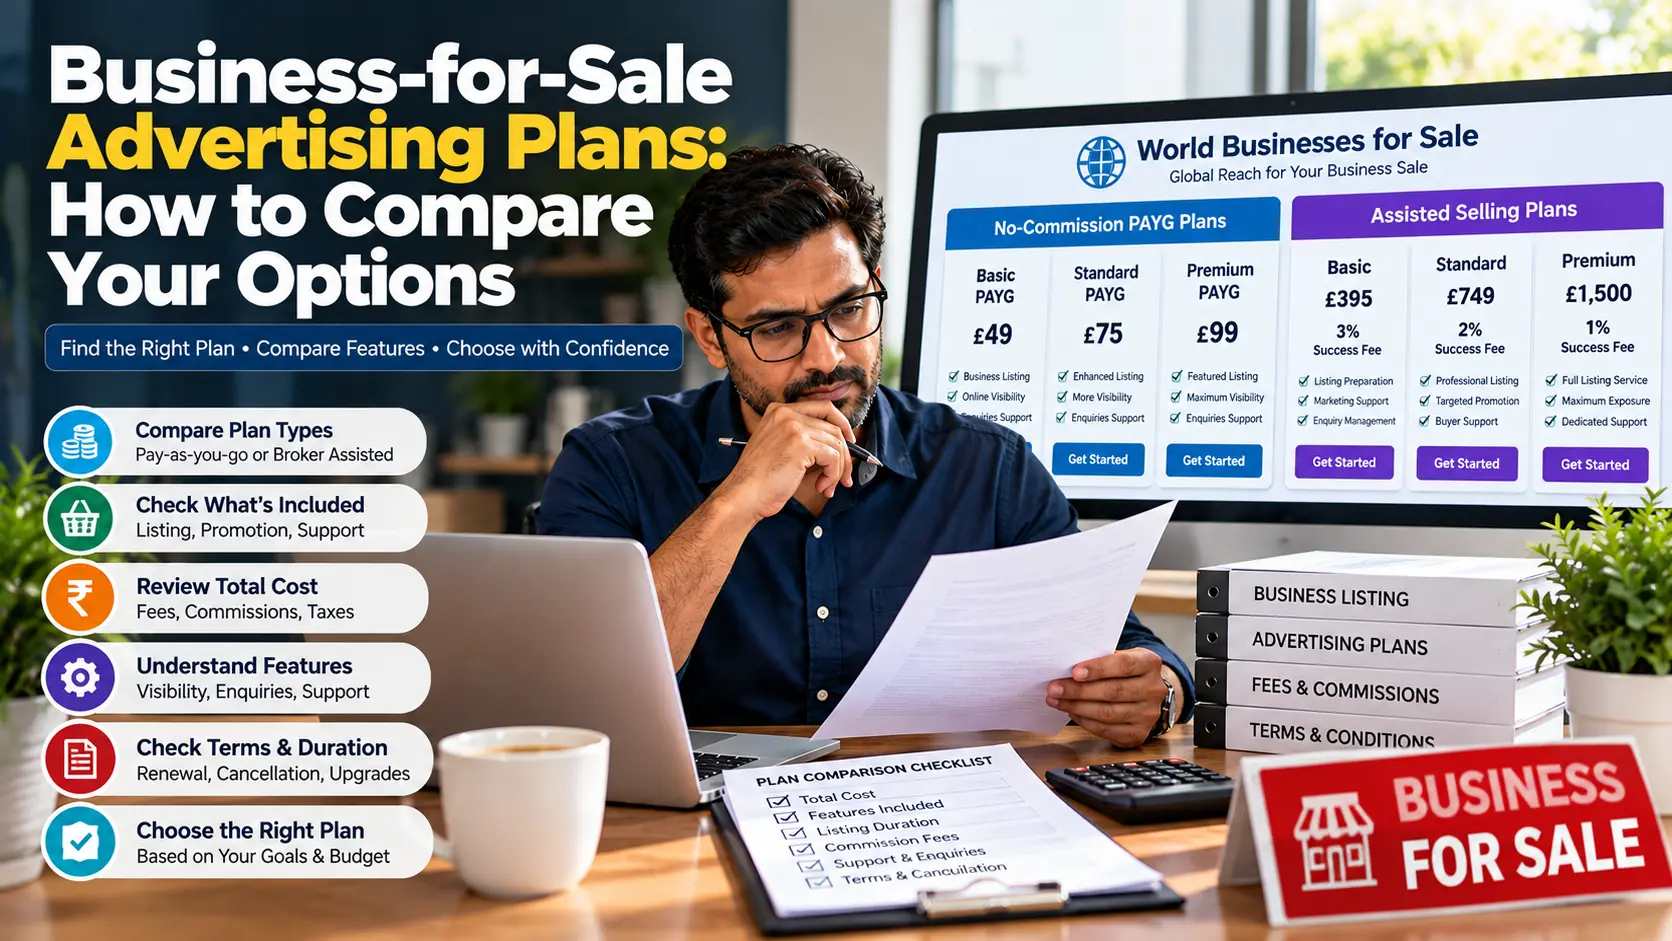
Online marketplaces can provide a way to present your opportunity to people actively researching businesses for sale. However, the reach, audience, listing features, and commercial terms vary by platform.
Before paying for a listing, compare its pricing, duration, visibility options, enquiry process, and any additional fees.
You can explore the advertising options available through World Businesses for Sale. Review the current plan descriptions and terms on the platform before choosing an option.
11. Prepare for Buyer Questions
Potential buyers may ask about profitability, competition, customer retention, staff, operating costs, and future prospects.
Prepare clear, evidence-based answers to common questions, including:
- What are the main sources of revenue?
- How stable is the customer base?
- What are the largest operating expenses?
- Does the business depend heavily on the current owner?
- What assets and liabilities are included?
- Why is the owner selling?
- What training or transition support may be available?
You do not need to publish every detail in your public listing. Keep supporting documents organised so that relevant information can be shared at the appropriate stage.
Be honest when you do not have an answer immediately. Confirm the information rather than guessing.
12. Evaluate Buyers and Plan the Transition
An interested buyer is not necessarily a qualified buyer. Before progressing too far, consider their financial capacity, relevant experience, intended timeline, and ability to meet the proposed terms.
Depending on the transaction, you may need professional help with buyer screening, confidentiality agreements, due diligence, negotiation, contracts, and completion.
Also decide what transition support you are prepared to offer. Some buyers may request training or an introduction to key suppliers and customers. Agree on the scope, duration, and compensation for any ongoing involvement before committing.
Do not treat an initial enquiry or verbal offer as a completed sale. The transaction may still depend on due diligence, financing, approvals, and signed agreements.
Business Sale Preparation Checklist
Before publishing your listing, check that you have:
- Defined your selling objectives and preferred timeline
- Organised recent financial statements and tax records
- Reviewed the asking price with appropriate professional advice
- Prepared a list of assets and liabilities
- Documented important operating procedures
- Reviewed contracts, licences, and legal obligations
- Identified confidential information requiring protection
- Written an accurate business overview
- Prepared answers to common buyer questions
- Compared advertising platforms and their current terms
- Planned how buyer enquiries and the transition will be handled
You do not need to complete every task alone. An accountant, lawyer, business valuer, or broker may be useful depending on the complexity of your business and the proposed transaction.
Frequently Asked Questions
How long should I prepare before selling my business?
There is no universal timeline. A straightforward business with organised records may be ready sooner than one with incomplete accounts, complex contracts, or operational issues. Begin early enough to address problems without rushing important decisions.
Should I advertise my business before setting an asking price?
It is generally better to establish a reasoned pricing approach before publishing a listing. You can then communicate your expectations more clearly and respond consistently to buyer enquiries.
Do I need a business broker to sell my business?
Not every seller uses a broker. Some owners manage the advertising and initial enquiries themselves, while others engage a professional for valuation, buyer screening, negotiation, or transaction support. The appropriate choice depends on the size and complexity of the sale.
Should I disclose my business name in the public listing?
That depends on your confidentiality requirements and the platform's available listing options. If secrecy is important, investigate whether an anonymous or confidential listing is available and learn how interested buyers are screened before sharing identifying details.
Does advertising guarantee that my business will sell?
No. Advertising can help present your business to potential buyers, but a sale depends on factors such as pricing, business performance, market conditions, buyer suitability, financing, and the terms of the transaction.
Final Thoughts
Preparing your business for sale is an opportunity to organise its finances, improve operational clarity, and present the opportunity professionally.
Start with accurate records, a realistic valuation, clear documentation, and a well-written listing. Then compare suitable advertising channels and establish a process for handling enquiries confidentially.
If you are ready to explore online advertising options, visit World Businesses for Sale and review the current plans to decide which option fits your selling goals and budget.
A well-prepared listing cannot guarantee a sale, but it can help you approach the process with greater clarity and confidence.